


This article was produced for ProPublica’s Local Reporting Network in partnership with Tennessee Lookout . Sign up for Dispatches to get stories like this one as soon as they are published.


Jeanette Thomas had just made her first payment on a loan from payday lender Advance Financial when she said the company emailed her with “good news.” She could borrow $206 more.
The solicitation was a relief to Thomas, a 62-year-old grandmother who had already exhausted the $783 disability check she receives each month since her health conditions render her unable to work.
Over the next few months, Thomas made the required minimum payments on what started in 2019 as a $400 loan to buy Christmas presents. But each time she did so, the company invited her to borrow almost all of the payment back, she said, with emails or letters like “Access Your Cash Today” or “You’re Already Approved.”

“They kept trying to rope me in,” Thomas said.
In the months that followed, the company continued to expand her credit, allowing Thomas to borrow close to $1,600 in total. In the emails and letters that Thomas kept, Advance never stated how much it would cost if she continued to reborrow.
Thomas had read her original loan documents warning that the loan carried a high 279.5% interest rate and would be challenging to pay off. But as the loan balance grew, Thomas came to realize she was trapped. By the spring of 2021, Thomas had paid Advance almost $4,000, yet she still owed more than $1,000 and was paying more than $200 a month to cover the interest, depleting the disability checks that were her only source of income.
Until the Flex Loan, reborrowing or rolling over payday loans was against the law. Tennessee lawmakers first banned reborrowing when they passed the state’s payday lending law in 1997. They reaffirmed that protection in 2011 when they updated that law.
When Tennessee lawmakers passed a 2014 law allowing Flex Loans, they included no such provision.
Instead, the bill’s sponsor, current House Speaker Cameron Sexton, said the loans could be better for borrowers because it required them to make a monthly minimum payment that covered all fees, interest and 3% of the principal. This key provision would ensure that borrowers would always be paying down the principal on the loan.
Thomas and more than a dozen borrowers told the Tennessee Lookout and ProPublica that Advance has encouraged them through emails and notifications to borrow back the value of almost all of the payments they made, tearing a hole in the safety net the law tried to put in place.
All but one of the 14 borrowers who spoke to the newsrooms for this story reported having reborrowed at least once as part of their Advance loan. As with Thomas, Advance made them eligible to borrow more shortly after paying, even though they were often making the minimum payments and almost immediately borrowing the money back to cover the cost of the payment they just made. Advance went on to sue 12 of these borrowers once they stopped being able to afford the loan.

Credit:
Obtained by Tennessee Lookout and ProPublica. Highlighted and redacted by ProPublica.
Andrea Heady, 45, was sued by Advance in Knoxville for over $7,300, despite having paid the company nearly double what she ultimately borrowed. She initially took out $750 through a Flex Loan after the hours at her university job were slashed in June 2020.
“I’ve always sent money home to my mom,” who was taking care of Heady’s sister, she said. “It was COVID. My aunt and uncle were very sick, then they passed away and I just needed money.”
Heady said Advance would send her notifications letting her know she could borrow more. One email appeared as a financial statement, but included in bold and large text was the amount she had available to borrow. The statement did not provide a payment schedule, a new loan amount, the total cost of the loan or how long it would take to pay off making minimum payments, information a lender would have been required to provide if she’d been borrowing on a credit card.
Credit:
Stacy Kranitz for ProPublica
Heady reborrowed on her Flex Loan over a dozen times over the next 18 months as Advance increased her credit limit seven times. She stopped paying when her monthly payments of $650 equaled a quarter of her paycheck.
Heady hoped the company would forget about her, but it didn’t. In 2024 Advance sued and won a wage garnishment against her. Ultimately, Heady will end up paying Advance over $14,000 on the $3,850 she borrowed.
David Hill, a 36-year-old from Nashville, started by borrowing $175 from Advance in February 2020. Each month he would repay the full borrowed amount, including interest and fees, and reborrow the principal, often on the same or next day. Over 18 months, he reborrowed almost 80 times.
“COVID happened and I was going through financial trouble,” Hill said. “I would get a check and pay it off. But then I would have to borrow it back to have money.” 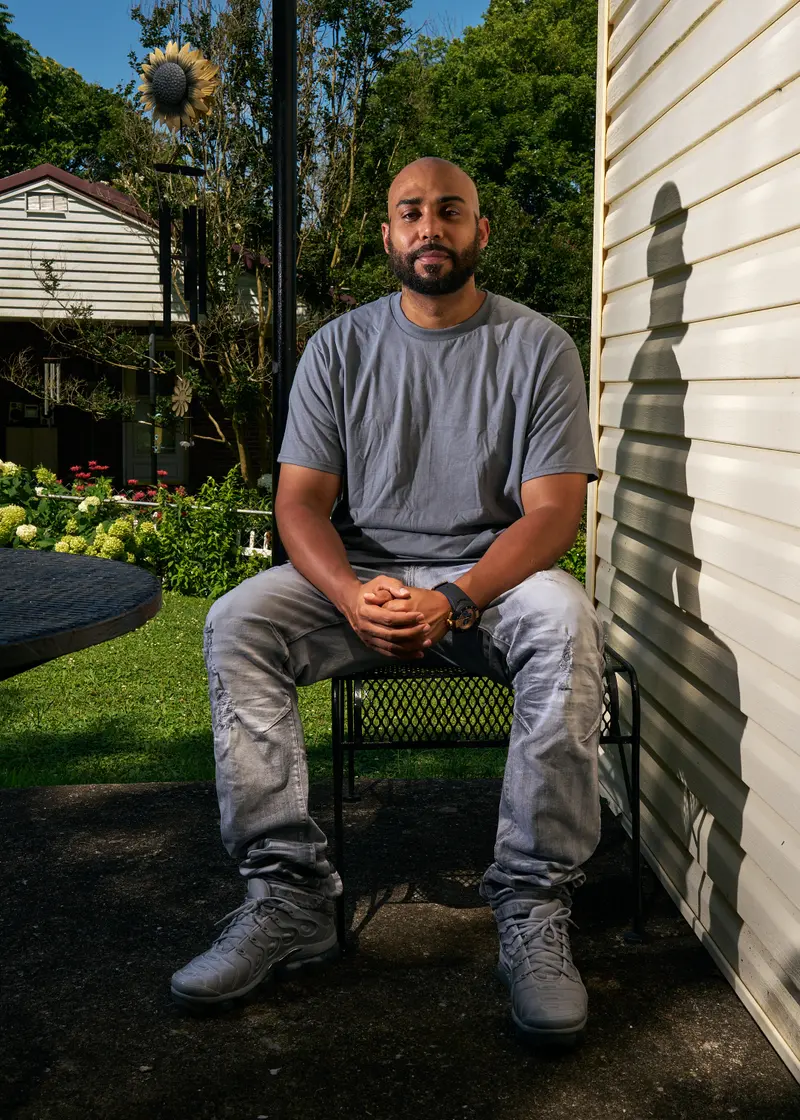
Credit:
Stacy Kranitz for ProPublica
Via email, Advance kept increasing his credit limit and encouraging him to borrow more. “Dear David,” started two of the emails, which contained notes like “good news — you have $645 available.” Hill eventually reached a point where he couldn’t afford the minimum payment, totaling over $400 a month.
He stopped paying and the company sued him in 2023 for over $4,700.
The Lookout and ProPublica sent detailed questions to Cullen Earnest, the senior vice president of public policy at Advance Financial. Earnest repeated what he said in a previous statement, that the company has an A+ rating from the Better Business Bureau. He added that the Tennessee Department of Financial Institutions has received just 91 complaints about flexible credit lenders since 2020, representing less than 0.001% of all new flex loan agreements, and that this data reflects the satisfaction of the vast majority of Advance’s customers.

